What to Do If Your Bank Charges an Unexpected Fee
You check your balance on a Tuesday morning and the number is lower than it should be. Then you spot it: a $35 "maintenance fee" or a $12 "overdraft item fee" you never agreed to and never saw coming. Your stomach drops a little. That money was already spoken for.
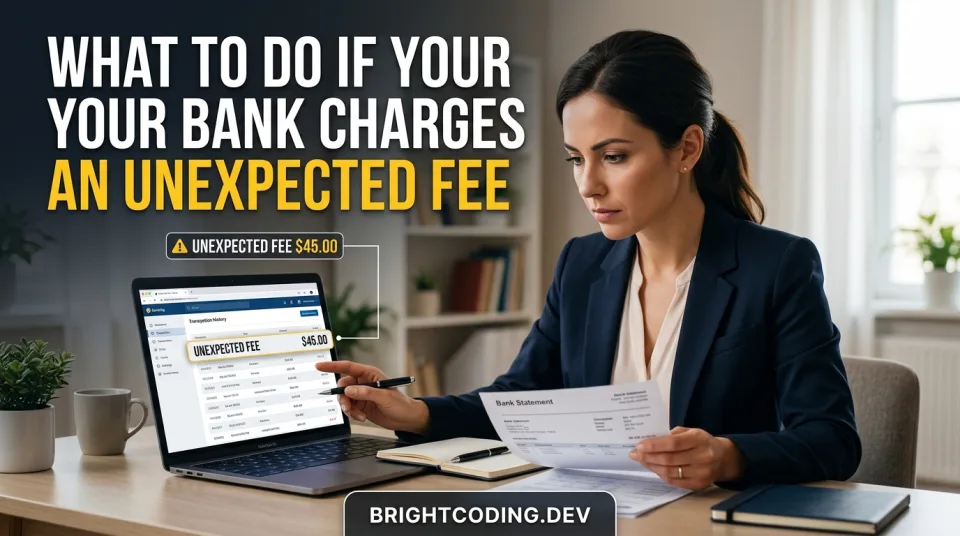
You check your balance on a Tuesday morning and the number is lower than it should be. Then you spot it: a $35 "maintenance fee" or a $12 "overdraft item fee" you never agreed to and never saw coming. Your stomach drops a little. That money was already spoken for.
Here's the good news. A large share of unexpected bank fees can be reversed, refunded, or avoided entirely going forward, and it usually takes one phone call. This guide walks you through why these charges appear, how to fight them, and how to stop them from coming back.
The Problem: Money You Didn't Plan to Lose
An unexpected fee is not just annoying. It can trigger a chain reaction. A $35 overdraft fee pushes your balance further into the negative, which triggers another fee, which then bounces a scheduled bill, which adds a late charge from the merchant. One small charge snowballs into fifty or a hundred dollars gone in a week.
The people hit hardest are rarely the wealthy. They're people living close to the edge of their balance, students, gig workers, parents juggling multiple bills, anyone who doesn't have a cushion to absorb surprises. Banks know this, and that's exactly why some of these fees exist.
The mistakes people make
Most people do one of three things when they see an unexpected fee. They ignore it and hope it goes away (it won't). They get angry and call without any information ready (which rarely goes well). Or they switch banks in frustration without fixing the underlying pattern, so the same fees follow them to the new account.
The smartest move is the boring one: understand the charge, then ask for it back.
Why Banks Charge Fees You Didn't Expect
Fees don't appear out of nowhere, even when they feel like they do. A few common causes explain most of them.
The fee schedule changed. Your bank updated its terms and sent you a notice buried in a statement insert or an email you skimmed. That free checking account might now require a minimum balance or a monthly direct deposit to stay free.
Your balance dipped below a threshold. Many accounts waive the monthly maintenance fee only if you keep, say, $1,500 in the account or receive regular deposits. One low month and the fee kicks in.
A transaction posted in an order you didn't expect. You had $200 in the account, you spent $180, and a $25 subscription hit the same day. The bank processes the larger transactions first, your balance drops, and now you're overdrawn. This ordering practice has been the subject of real regulatory scrutiny in several countries.
A subscription you forgot about. Free trials that convert to paid plans, annual renewals, that app you downloaded two years ago. These are the silent fee generators.
A "courtesy" overdraft. Your bank let a payment go through instead of declining it, then charged you for the courtesy. This is legal in many places but you can usually opt out.
If you want to understand how financial surprises fit into a broader emergency plan, our practical guides cover the basics of staying prepared when money gets tight.
The Solutions: Five Realistic Ways to Handle It
1. Call and ask for a refund
What it is: A direct request to customer service to reverse the charge.
How it works: You call the number on the back of your card, explain the fee was unexpected, and ask them to waive it. First-time requests are frequently granted, especially if you're a customer in good standing.
Advantages: Free, fast, often successful. Many banks have informal policies allowing a certain number of refunds per year per customer.
Disadvantages: Not guaranteed. Repeat requests get denied. Some phone queues are brutal.
When it makes sense: Always try this first, for any fee over a few dollars.
Cost: Just your time. Budget 15-30 minutes including hold time.
2. Switch to an account with no overdraft fees
What it is: Moving your money to a bank or credit union that doesn't charge overdraft or nonsufficient funds fees.
How it works: Some banks and many online banks now offer accounts with no overdraft fees at all, or they simply decline transactions that would overdraw you instead of letting them through and charging.
Advantages: Eliminates the problem at the root.
Disadvantages: Switching is a hassle. You need to update direct deposits, autopay, and linked accounts. Some no-fee accounts have other tradeoffs, like no physical branches.
When it makes sense: If you've been hit with fees more than twice in a year, seriously consider it.
3. Opt out of overdraft "coverage"
What it is: Telling your bank you do not want them to cover transactions that would overdraw your account.
How it works: You contact the bank or toggle the setting in your app. From then on, a purchase that would overdraw you gets declined instead. In the US, banks are required to get your consent before charging overdraft fees on debit card and ATM transactions, so opting out is your right.
Advantages: No more surprise overdraft fees.
Disadvantages: Your card may be declined at the register, which is embarrassing and can leave you without funds in a genuine emergency.
When it makes sense: If you'd rather be declined than charged, this is a clean fix.
4. Negotiate a better account tier
What it is: Asking your bank to move you into a fee-free account type or waive requirements.
How it works: Sometimes a simple request, "Can you switch me to the account without the monthly fee?" does it. Loyalty and deposit history give you leverage.
Advantages: Keeps your existing account and setup intact.
Disadvantages: You may need to meet a condition, like a minimum direct deposit or a certain number of debit transactions per month.
5. File a formal complaint
What it is: Escalating beyond the bank's customer service.
How it works: In the US, you can file a complaint with the Consumer Financial Protection Bureau (CFPB). Similar ombudsman services exist in the UK, Australia, Canada, and across the EU. Banks take these complaints seriously because they're tracked and can lead to regulatory attention.
Advantages: Effective when the bank refuses to budge on a legitimate grievance.
Disadvantages: Slow. It's a last resort, not a first move.
When it makes sense: When you believe the fee was unfair or the bank violated its own terms, and you've already tried the direct route.
Which Option Fits Your Situation?
If it's a one-off fee and you're generally happy with your bank, call and ask for the refund. That's the fastest, easiest win.
If fees keep appearing month after month, the refund call is a bandage. You need the structural fix: opt out of overdraft coverage, or move to a no-fee account.
If you're living paycheck to paycheck and can't maintain a minimum balance, a no-fee online account or a credit union is often the better home for your money than a big traditional bank.
If the bank did something clearly wrong, like charging a fee after you'd already opted out, escalate. That's when a formal complaint is worth the effort.
There's no single right answer here. It depends on your balance, your banking habits, and how much hassle you're willing to take on.
If you're dealing with a wider financial squeeze and want to think through other emergencies too, our blog has practical write-ups on handling unexpected costs of all kinds.
Step-by-Step Action Plan
-
Identify the fee. Look at your statement or app. Note the exact name, amount, and date. You'll need this for the call.
-
Check your account terms. Find the fee schedule, usually in your online documents. Confirm whether the fee is legitimate under your agreement.
-
Gather your case. Note how long you've been a customer, whether you've had fees reversed before, and whether the charge was a genuine mistake on your part.
-
Call customer service. Be polite, be specific, and ask directly: "Can you reverse this fee as a one-time courtesy?" Polite persistence beats anger almost every time.
-
If declined, ask for a supervisor. Escalate calmly. Ask what would need to be true for the fee to be waived.
-
Fix the root cause. Opt out of overdraft coverage, set up low-balance alerts, or switch accounts.
-
Cancel forgotten subscriptions. Go through your recurring charges and kill anything you don't actively use.
-
Escalate formally if needed. File a complaint with your country's consumer financial regulator.
-
Set a reminder to review. Look at your statement once a month for three months. You'll catch the next surprise before it stacks up.
For urgent situations where money problems overlap with a real emergency, keep the emergency numbers by country handy, and if you're managing this while caring for a family, our kids and family safety section has related guidance.
Common Mistakes to Avoid
- Ignoring the fee. It won't reverse itself. Fix: call within a few days of noticing.
- Calling angry. Yelling at a rep gets you a "no." Fix: stay calm and ask for help.
- Not knowing your account terms. You can't argue a fee if you don't know the rules. Fix: read the fee schedule once.
- Asking for refunds repeatedly. Banks track this. Fix: if you're asking every month, change the account, not the conversation.
- Switching banks without fixing the habit. The same fees follow you. Fix: change your behavior first, then the bank.
- Forgetting recurring subscriptions. They're the quiet fee factory. Fix: audit them quarterly.
- Not setting balance alerts. Most banks offer free low-balance texts. Fix: turn them on today.
Expert Takeaway
The single most useful habit here is simple: check your account weekly, not monthly. Fees compound, and the longer a charge sits, the harder it is to reverse. A two-minute glance every Sunday morning will save you more money than any negotiation tactic. If you want to go further, look for trusted financial help through our local provider directory, and remember this is general information, not professional financial advice. For your specific situation, talk to a qualified advisor.
FAQ
Can I get a bank fee refunded?
Often, yes. First-time requests are frequently granted as a courtesy, especially for customers in good standing. Call customer service, explain the charge was unexpected, and ask directly. No guarantees, but it costs nothing to try.
Why did my bank charge me a maintenance fee?
Usually because your account fell below a minimum balance or missed a required deposit. Check your account terms. Many banks waive the fee if you meet certain conditions.
How do I stop overdraft fees?
Ask your bank to opt you out of overdraft coverage. Then a transaction that would overdraw you gets declined instead of covered and charged. In the US, banks must get your consent before charging overdraft fees on debit and ATM transactions.
Is it worth switching banks over fees?
If you're paying fees more than once or twice a year, yes. No-fee accounts exist at many online banks and credit unions. Just fix your balance habits first, or the fees may follow you.
Who can I complain to about an unfair bank fee?
In the US, the Consumer Financial Protection Bureau (CFPB). In the UK, the Financial Ombudsman Service. In Canada, the Ombudsman for Banking Services and Investments. In Australia, the Australian Financial Complaints Authority. Most countries have a similar regulator. File only after you've tried the bank directly.
Written by
Michael Carter
Safety and first-aid editor dedicated to creating practical guides that help people understand what to do during emergencies and unexpected situations.
Spotted an error? Report it — we correct mistakes promptly.
Keep reading
Related articles
What to Do If You’re Running Out of Money Before Payday
It's the 22nd of the month. Rent cleared. The electric bill cleared. Your account balance says $43.17, and payday is still nine days away.
10 Money Mistakes That Keep People Poor
Money feels personal, but the mistakes that keep people stuck are surprisingly predictable. Most aren’t about how much you earn. They’re about how you handle what passes through your hands.
What to Do If You're Stuck During a Snowstorm
Stranded in a snowstorm? Learn the safest steps to survive, avoid deadly mistakes, and decide whether to stay in your car or walk for help.
Related guides
Change of address with your bank: what to do?
Change of address with your bank: the right reflexes in a few simple steps.
Tax refund delayed for weeks: what to do?
Tax refund delayed for weeks: the right reflexes in a few simple steps.
What To Do If Your Visa Application Is Delayed
Learn what steps to take when your visa processing is delayed, including checking your status, contacting immigration authorities, and adjusting travel plans safely.